


Cash Advance – Quick Borrow
4.830.00 Reviews
App Specs
- Version
- 1.0.7
- Updated On
- License
- Free
- Downloads
- 10,000+
- Developer
- TIMECORE Studio
- Categories
- Finance
- Platform
- Android
Screenshots
 Analysis by AppCompare
I approached Cash Advance – Quick Borrow as a practical finance app rather than something to browse casually. Its purpose is straightforward: it gives people a way to request cash advance and personal loan offers online, with the emphasis on making the initial request quick. My overall view is that it can be useful when you need to explore borrowing options without visiting a branch, but it should be treated as an offer-comparison and application tool, not as effortless money.
The app is free to install, carries an Everyone age rating, and comes from TIMECORE Studio. It sits in the finance category and has reached over ten thousand installs, with a 4.8 average from roughly nine hundred ratings. Those figures suggest that the basic experience has worked well for many users, although a high store score should never replace careful reading of the terms attached to any offer.
What the borrowing experience is really good at
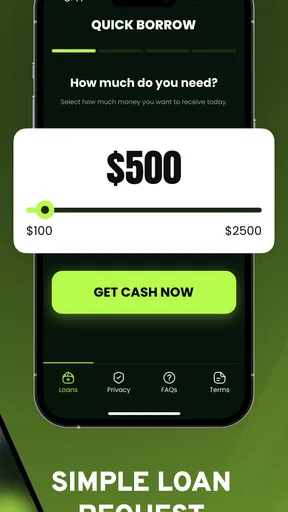
The clearest strength is convenience. Instead of beginning with a search across several lender websites, I can start inside one mobile interface and submit a request for cash advance or personal loan offers. That matters most when I am trying to understand what may be available quickly, especially outside normal branch hours or when I would rather keep the first step private and digital.
There is also a useful psychological advantage to separating the request stage from the borrowing decision. I can use the app to investigate possibilities before deciding whether any offer makes sense. That is a healthier workflow than accepting the first advert that appears in a search engine, because the app gives me a dedicated place to review the borrowing opportunity and think about the repayment obligation.
In everyday use, I would see this being most helpful for a short-notice expense such as an urgent household repair or a necessary bill that cannot reasonably wait. I would open the app, make the request when I have the relevant personal and financial details nearby, then pause before accepting anything. The important part of that scenario is the pause: the app can speed up discovery, but it should not speed up judgment.
One practical tip is to prepare before opening the request form. I would have my regular income information, current monthly commitments, and a realistic repayment amount in mind. Even if the form itself is fast, entering figures without thinking about the monthly effect can make an offer look more attractive than it really is. A quick request is valuable only when the information behind it is accurate.
Another useful habit is to read every screen as part of the financial decision, not merely as a step to tap through. A person looking only for the fastest possible result may focus on whether an application can be sent quickly. I would instead look for the total repayment, timing, fees, and consequences of missing a payment wherever those details appear in the offer process. The app’s convenience should make careful checking easier, not encourage skipping it.
Worth Reading Before You Choose

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy

ESPN’s Live Game View Makes Following Close Games Easier
The app’s current version is 1.0.7 and it supports devices running Android 7.0 or later. That gives it a broad compatibility range for people using older Android phones, which is relevant for a finance tool because not everyone keeps a recent device. I would still keep the operating system updated where possible, especially when handling sensitive financial information.
Its presentation is also helped by a focused purpose. This is not a budgeting suite trying to combine spending charts, investment tracking, bill reminders, and banking tools in one place. The narrow focus makes sense for someone who has already decided to investigate borrowing and wants a direct starting point. If I only need expense tracking, however, installing a loan-request app would be the wrong solution.
How it compares with familiar alternatives
The usual alternatives are contacting a bank directly, visiting a local lender, or searching online for individual providers. A bank may offer a more familiar relationship and clearer access to an existing account, while a branch can be useful for people who want face-to-face explanations. On the other hand, those routes can take more time and may make it harder to begin comparing possibilities privately.
Cash Advance – Quick Borrow is more convenient at the opening stage than a branch visit. It is also more focused than a general search engine, where advertisements and unrelated results can make it difficult to tell what deserves attention. The trade-off is that a dedicated app does not automatically mean that every offer is suitable, inexpensive, or available to every user. I still need to examine the actual terms with the same care I would use on a lender’s own website.
Compared with a credit union or an established bank, the app’s strongest advantage is speed of access to the request process, not necessarily the cost of borrowing. If I already have a trusted financial provider and can obtain a transparent loan quote there, that direct route may be better. If I need to explore options efficiently, this app can be a sensible first step, provided I use it to gather information rather than to make an impulsive commitment.
The friction that matters before you apply
The most meaningful limitation is built into the subject itself: a fast request does not guarantee fast approval, favorable terms, or money in my account. The app can help me submit a request and view loan possibilities, but the final outcome depends on the offer and the lender’s assessment. Anyone installing it expecting guaranteed cash is approaching it with the wrong expectation.
There is also a risk of confusing an available offer with an affordable offer. A person under pressure may see a borrowing option as a solution simply because it appears quickly. I would calculate the full repayment before accepting anything and compare it with my normal monthly surplus. If the payment would leave no room for food, transport, rent, utilities, or an unexpected expense, the offer is not truly affordable even if the application feels easy.
Privacy deserves deliberate attention as well. Finance applications involve personal information, so I would read the app’s on-screen explanations and permissions carefully before submitting details. I would avoid using a public Wi-Fi network for the request, keep the phone protected with a lock screen, and never share verification codes with another person. These are not reasons to dismiss the app; they are sensible boundaries for any mobile borrowing process.
A further point is that the app should not become a repeated emergency shortcut. Using borrowing to cover one isolated, unavoidable cost is different from relying on advances to pay ordinary monthly expenses. If I found myself returning to the app every pay cycle, I would stop applying and review my budget, negotiate bills where possible, or seek independent financial guidance. The convenience that makes the app helpful in a genuine short-term situation can become a problem when it hides an ongoing shortfall.
I would also be cautious about entering a request while tired, rushed, or emotionally stressed. The app’s quick online format is useful, but those conditions make it easier to overlook a repayment schedule or accept an amount larger than necessary. My preferred workflow would be to request only what the emergency requires, save or note the important offer details, and revisit them after a short break before making a final decision.
Who will get the most value from it
This app is best suited to an adult who understands that it is a starting point for cash advance and personal loan offers. It fits someone who values a mobile-first process, wants to investigate borrowing without a branch appointment, and is prepared to compare the practical cost of repayment. The free download lowers the barrier to exploring the service, but it does not remove the financial responsibility that follows.
I would recommend it more confidently to a person with a specific, limited need and a clear repayment plan. For example, if an essential expense arrives before payday and I know exactly how the next income will cover the obligation, the app may help me explore a short-term option efficiently. Even in that case, I would borrow the smallest reasonable amount and keep a record of the due dates.
It may also suit users with older Android phones, since the minimum operating system is Android 7.0. That is a practical advantage for people who cannot or do not want to replace a working handset simply to use a finance app. The app’s Everyone rating makes it broadly accessible from a store perspective, but the subject matter still calls for adult financial judgment and careful supervision of personal decisions.
I would tell several groups to skip it. Someone seeking a budgeting tool, savings tracker, investment platform, or detailed debt-management system will not find a loan-request app to be the right category of product. A person who already knows that they cannot meet another repayment should not use a fast application process to postpone the underlying problem. And anyone who prefers a long-standing relationship with a bank or local adviser may receive better guidance by speaking directly with that provider.
A safer way to use the app
My recommended workflow begins before the first tap. I would write down the exact amount needed and separate essential costs from optional spending. Then I would estimate the largest monthly payment I could handle without relying on another advance. This prevents the form from deciding the size of the problem for me.
After submitting a request, I would review each offer slowly. I would check the amount received, the total amount repaid, the payment frequency, the first due date, and any stated fees or penalties. I would also check whether the repayment timing matches my income schedule. A payment that looks manageable in isolation may be awkward if it arrives before wages or other regular income.
I would compare the app’s offers with at least one direct alternative, such as my existing bank or a reputable local financial provider. The point is not to collect endless applications; it is to avoid assuming that the first convenient option is the cheapest or most suitable. I would keep the comparison focused and stop once I had enough clear information to make a responsible decision.
Finally, I would save the agreement details securely and set a personal reminder for the payment date. I would not depend on memory or assume that an app notification is the only safeguard. This small extra step is one of the most useful ways to turn a quick digital request into a controlled financial commitment.
TIMECORE Studio has made a focused tool for people who want to begin a borrowing request online. The combination of a free app, broad Android compatibility, and a strong store response makes it approachable, and the narrow purpose keeps the experience more direct than a general-purpose finance application. Those are genuine strengths for a user facing a time-sensitive need.
My reservation is equally clear: speed can improve access, but it cannot make debt harmless. The app is not the right choice for someone looking for guaranteed approval, effortless money, or a replacement for budgeting and financial advice. Its value depends on how carefully I examine the offer after the request is made.
Overall, I would recommend Cash Advance – Quick Borrow as a convenient research and application starting point for a specific short-term need, not as a routine financial safety net. If I had a defined expense, a credible repayment plan, and the patience to compare the final terms, I would consider trying it. If any of those pieces were missing, I would choose a slower but more personal alternative instead.
Pros
- Fast application process with minimal paperwork
- Clear repayment terms shown before accepting an advance
- Useful for covering unexpected short-term expenses
- Simple interface that is easy for first-time borrowers
- Loan status and payment information are easy to track
Cons
- Approval and borrowing limits may vary by applicant
- Fees can make short-term borrowing expensive
- Late payments may lead to additional charges
- Not available in every region or to all users
- Requires careful budgeting to avoid repeated borrowing
FAQs for Cash Advance – Quick Borrow
What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account, you typically provide personal and financial information, review available offers, and submit a request. Approval, loan amount, fees, repayment terms, and funding speed depend on the provider’s assessment and your individual eligibility.
Who can use Cash Advance – Quick Borrow, and what information is required?
Eligibility requirements may vary depending on your location, the lending partners available through the app, and your financial profile. Applicants are commonly asked to provide identification details, contact information, employment or income information, banking details, and permission for certain verification checks. You should read the app’s eligibility rules and privacy policy carefully before submitting sensitive information.
How much does borrowing through the app cost?
The total cost can include interest, origination charges, service fees, late-payment fees, or other expenses, depending on the offer presented to you. Do not rely only on the advertised advance amount or speed. Before accepting anything, review the annual percentage rate, total repayment amount, payment schedule, and all applicable fees so you understand the real cost of borrowing.
How quickly will the money arrive after approval?
Funding times are not guaranteed and can depend on approval, identity verification, banking hours, weekends, your bank, and the selected funding method. Some users may receive funds quickly, while others may experience delays or additional verification requests. The app should display an estimated delivery time, but you should confirm the exact terms before completing the request.
Is Cash Advance – Quick Borrow safe to use?
Before using the app, verify that it is available legally in your region and identify the actual lender or financial service provider behind any offer. Check the developer information, permissions, privacy policy, customer reviews, and customer-support details. Never share passwords, verification codes, or unnecessary banking credentials, and avoid accepting an advance until you fully understand repayment obligations and privacy practices.


